Scottsdale and Phoenix Housing Market Update: August 2026
The number I am watching from August is 4.28 months of supply. That is up 13.47% from July even though active listings actually fell during the month. Closed sales dropped more than 13%, which means the increase in supply came from a slower pace of completed sales rather than another wave of homes hitting the market.
There was one encouraging change underneath that slowdown. Listings under contract increased 4.14% from July after falling sharply the month before. I want to see whether that improvement carries into September before reading too much into one month, but it gives us a more complete picture than the closed sales number alone.
That builds on what I covered in my July 2026 Scottsdale and Phoenix Housing Market Update, when sales and pending activity both weakened and the absorption rate dropped into the mid-26% range. August pushed it down again, this time to 23.37%. One note on that: ARMLS revises prior-month figures as late data comes in, so July's numbers shifted slightly between the July and August reports. I use whatever the most current report shows rather than the figure I published the month before.
The National Housing Market in August
August was softer nationally as well. The median list price fell to $424,500, down 1.3% from a year ago and 1% from July. That marked the tenth straight month of annual declines in asking prices, although the year-over-year decline was considerably smaller than July's 2.4%. Median list price per square foot fell 1.8% from last August.
Active inventory reached 1.14 million listings, up 3.6% year over year, while new listings fell 0.1%. The share of homes with a price reduction reached 20.4%, matching the prior year's level for the first time in 2026. Median time on market was 60 days, unchanged from August 2025 and three days longer than July.
The demand side weakened more noticeably. The stock of pending listings fell 0.2% year over year, ending eight consecutive months of annual growth, while new contract signings fell 3.7%. Mortgage rates added another affordability constraint, with the 30-year average reaching 6.67% in August, up from a 2026 low of 6.05% in February.
August is normally a slower month, so I would be careful about treating every monthly decline as a new trend. The combination of higher rates, fewer new contracts, and more price reductions does tell us that buyers were more selective as summer came to an end.
Phoenix Metro: What Changed in August
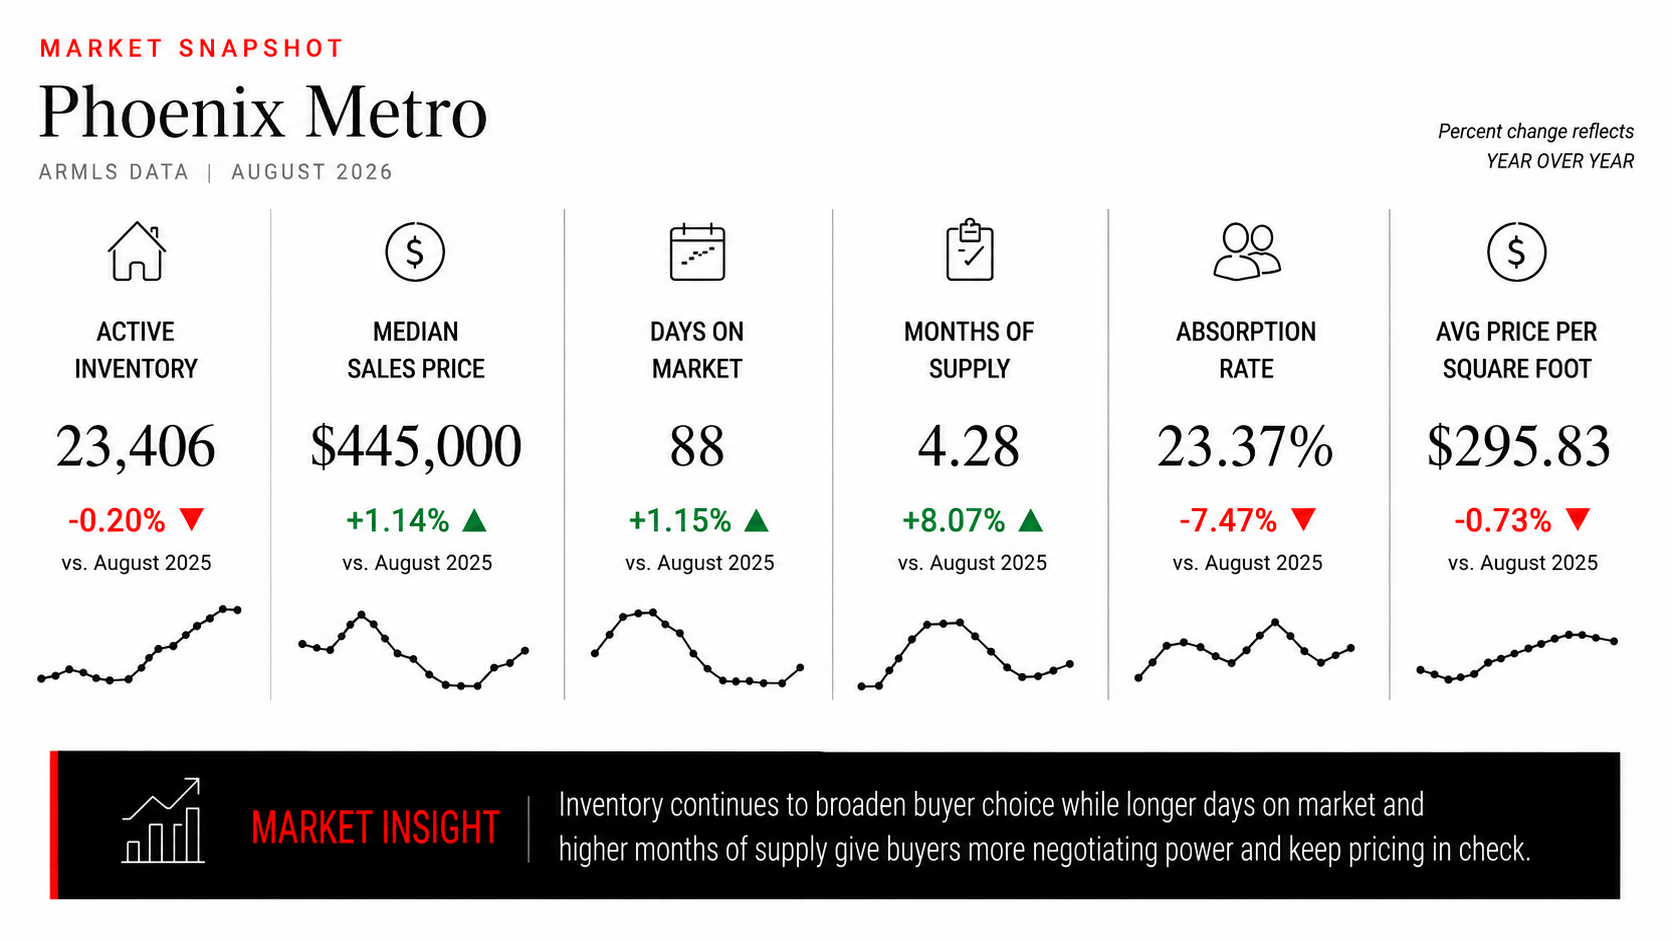
The ARMLS data gives us a closer look at the broader Phoenix-area market. The report covers ARMLS listing activity and notes that coverage can vary by area, so I use these numbers as a market-wide benchmark rather than a Scottsdale-specific measurement.
Closed sales fell to 5,471 in August, down 13.13% from July and 7.65% from August 2025. New listings totaled 8,173, down 1.83% for the month and 4.20% year over year. Active inventory excluding UCB and CCBS listings fell 1.43% from July to 23,406 and was almost identical to last August, down just 0.20%.
Under-contract activity moved the other direction. Pending, UCB, and CCBS listings increased from 6,638 in July to 6,913 in August, a 4.14% monthly improvement. That count was still 1.79% below August 2025, but the month-over-month increase matters after July's decline.
Months of supply rose from 3.77 in July to 4.28 in August, an increase of 13.47%. The absorption rate fell from 26.52% to 23.37%. Compared with August 2025, supply is 8.07% higher and absorption is 7.47% lower.
Prices softened at closing. The median sales price fell from $450,000 in July to $445,000 in August, down 1.11% for the month but still 1.14% above a year ago. Average sales price fell 3.42% from July to $579,032 while remaining 3.40% above August 2025. Median days on market increased from 61 to 64, although that was still three days shorter than a year ago.
Supply Rose Without an Increase in Active Inventory
This is the part of the August report I find most useful.
Active listings declined by 339 homes from July, yet months of supply increased from 3.77 to 4.28. The reason is the pace of sales. Closed transactions fell from 6,298 to 5,471 in one month. When fewer homes close, the existing inventory represents more months of supply even if the actual number of homes available has not increased.
That matters when interpreting what buyers are seeing. August did not bring a large influx of new inventory. New listings were actually down both month over month and year over year. Buyers gained time because the market absorbed the available inventory more slowly.
The under-contract count is the number I would pair with that. It increased 4.14% from July. Closings tell us what happened after contracts written in prior weeks worked their way through escrow. Pending activity gives us a better indication of what may be coming next. August had weak closings and a modest improvement in the contract pipeline. I want another month of data before deciding whether that improvement has legs.
What the August Numbers Mean for Scottsdale
The ARMLS numbers above should not be read as Scottsdale-specific statistics. Realtor.com's Phoenix-Mesa-Chandler data gives us another useful comparison, although that geography also extends well beyond Scottsdale.
In August, the Phoenix-Mesa-Chandler median list price was $475,000, down 4.8% from a year ago. Active listings were up 5.2% year over year and new listings were up just 0.6%. Price reductions appeared on 27.6% of listings, compared with 20.4% nationally. Median list price per square foot fell 1.4% year over year, while homes spent three fewer days on the market than they did in August 2025.
Those numbers show why I would be careful with broad statements about prices falling across Scottsdale. The Phoenix-Mesa-Chandler metro contains neighborhoods and price ranges that have almost nothing to do with each other. A remodeled home in Scottsdale Country Club does not compete with the same buyer pool as an entry-level home elsewhere in the Valley.
What I do take from the metro data is that sellers have more competition for buyer attention. More than one in four Phoenix-Mesa-Chandler listings had already taken a price reduction in August. That makes the initial pricing decision more important, especially when buyers have enough inventory to compare similar homes before writing an offer.
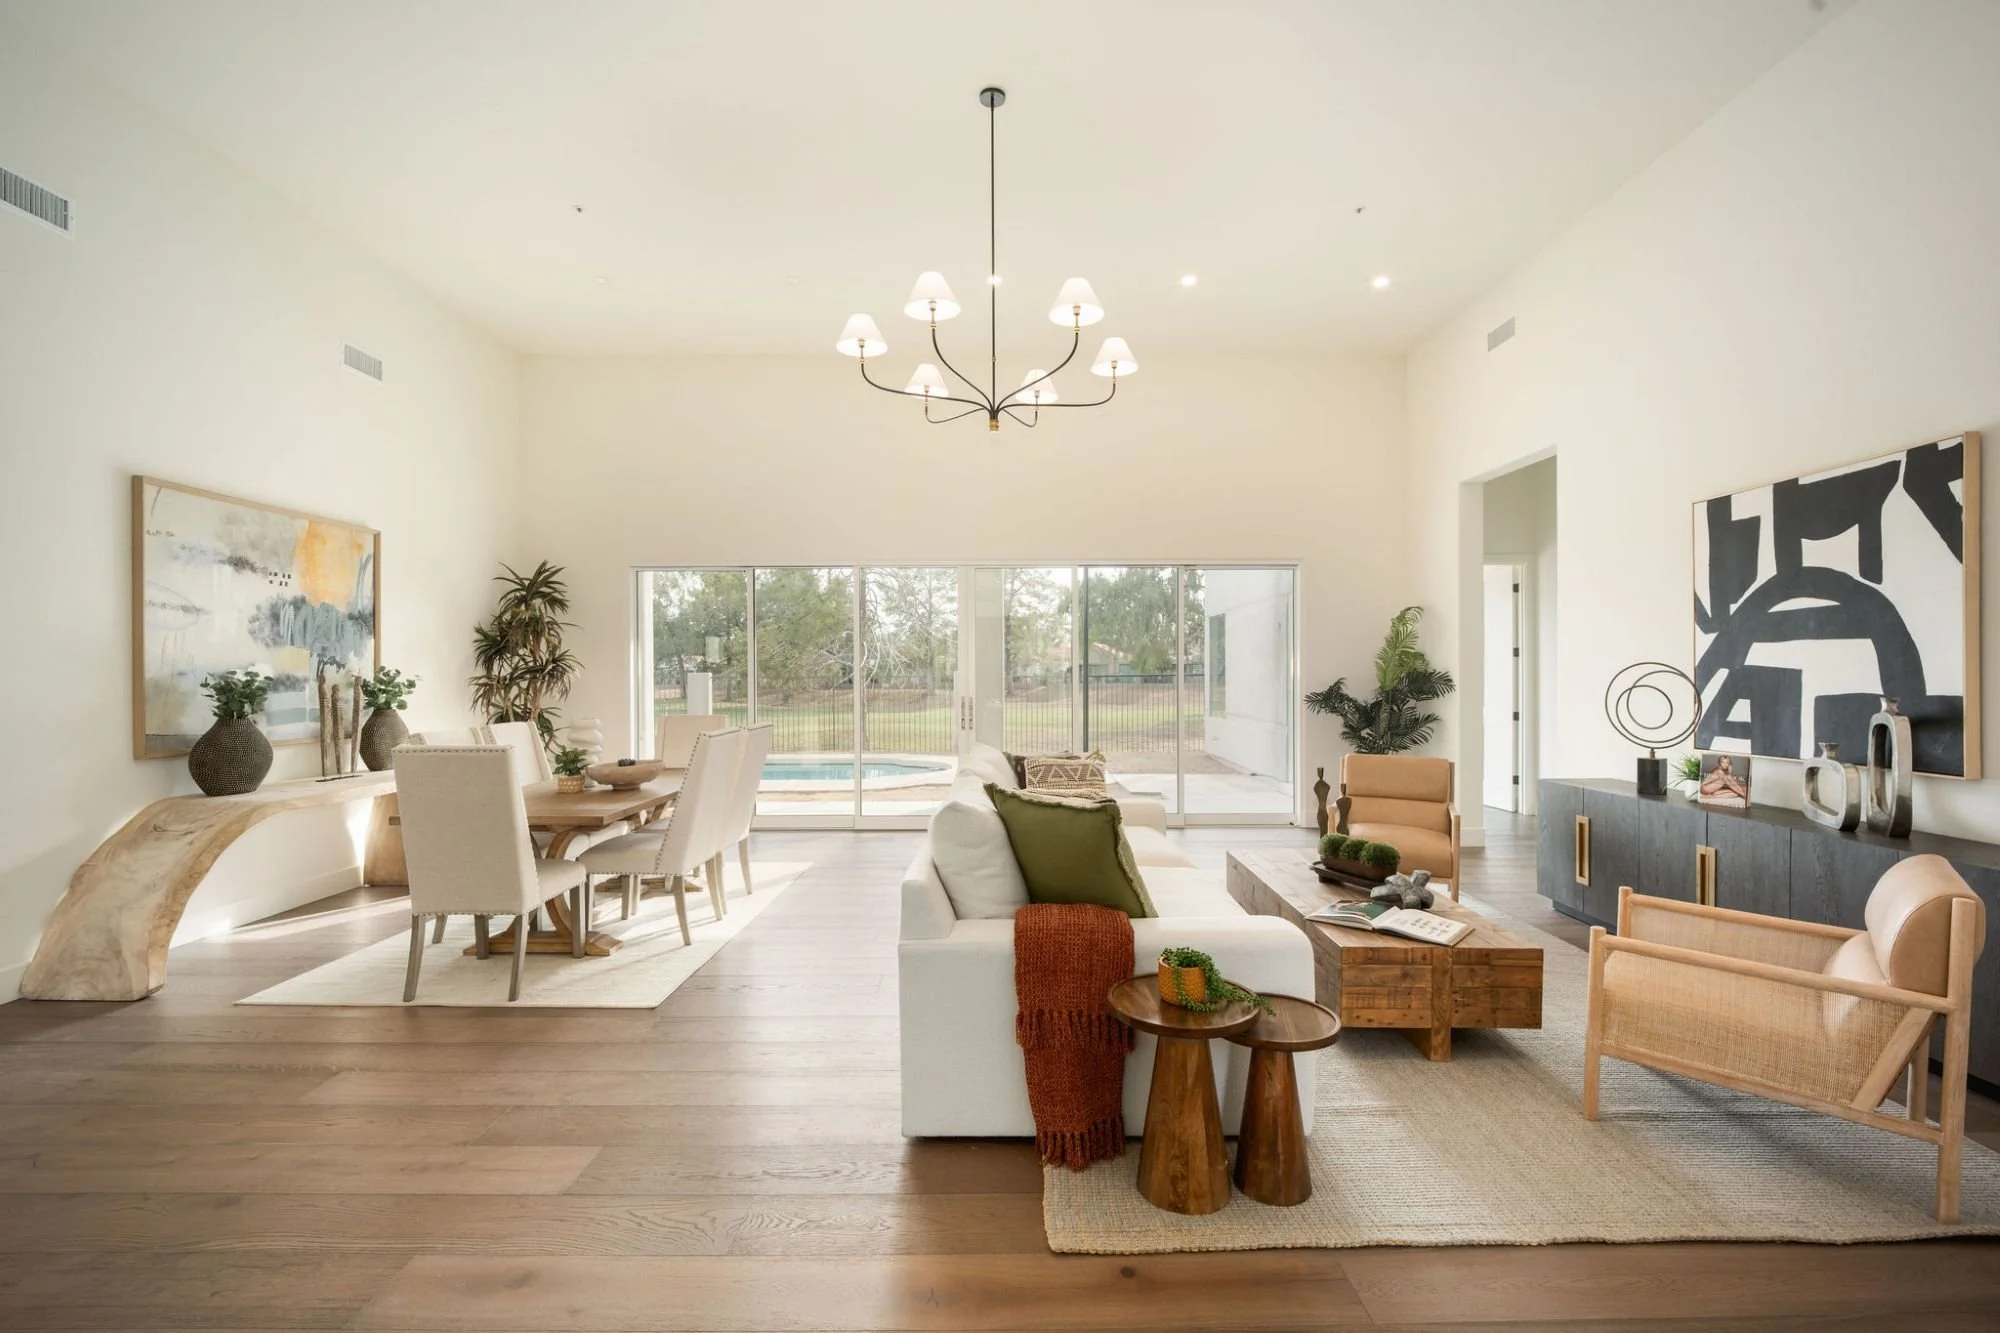
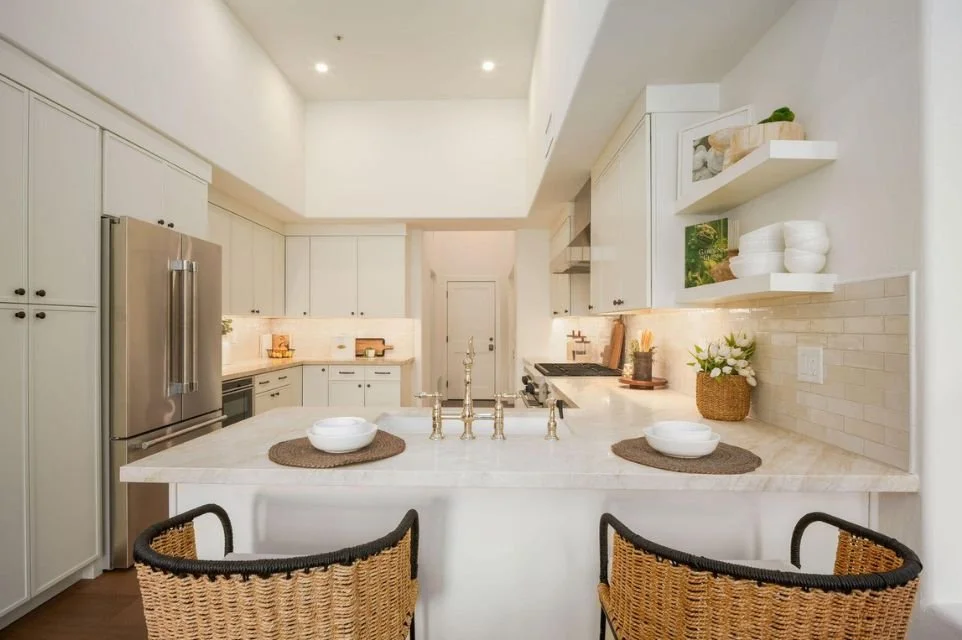
Check out my current listing in Scottsdale Country Club.
Currently listed at $1,899,999
What Buyers Are Walking Into Right Now
Buyers have more time than they did during the tighter parts of the spring market. At 4.28 months of supply, the broader ARMLS market is carrying 25.65% more supply than it did three months earlier, when the figure was 3.40 months. Median days on market has also moved from 56 days three months ago to 64 in August.
I would use that additional time to look closely at the things that actually move value on a specific property. Condition and renovation quality come first. Lot position and floor plan matter more than most buyers expect. HOA structure and recent neighborhood sales fill in the rest, and all of it tells you more than a metro-wide median ever will.
Buyers should also pay attention to how long a home has been listed and whether the seller has already adjusted the price. With 27.6% of Phoenix-Mesa-Chandler listings showing a price reduction in August, there are situations where the original asking price is already giving way to a more realistic number.
At the same time, I would not assume every seller is waiting for a low offer. Under-contract activity improved in August. A well-priced home can still attract attention even when the overall pace of sales is slower.
What Sellers Need to Understand About August
August gave sellers a fairly clear warning about overpricing.
The broader ARMLS market finished the month with fewer active listings than July, yet closed sales still fell more than 13%. Median days on market increased to 64, and the absorption rate dropped to 23.37%. Buyers did not need a surge of new inventory to become more selective.
There is also an interesting difference between new listings and closed sales. The median price of homes newly listed increased 1.70% from July to $462,740, while the median price of homes that actually sold fell 1.11% to $445,000. I would not interpret one month of that spread as proof that sellers are universally pricing too high, but it is something I am watching.
The Phoenix-Mesa-Chandler price-reduction rate reinforces the point. At 27.6%, reductions were considerably more common here than the national 20.4% rate.
For someone preparing to sell in Scottsdale, I would spend more time looking at the homes a buyer will compare directly against yours and less time anchoring to a sale from six months ago. August's numbers show a market that is giving buyers enough time to make those comparisons.
Scottsdale Luxury Market Perspective
August gives us a much better local luxury benchmark than we had in July.
Realt.com's August luxury report places the entry point for the top 10% of Phoenix-Mesa-Chandler listings at $1,240,243. The top 1% begins at $5,561,726, about 4.5 times the local luxury entry point. Million-dollar listings in the metro had a median market time of 82 days.
That spread is worth paying attention to because a $1.3 million property and a $5.5 million property technically sit within the same broad luxury category but operate in very different markets. It is one reason I avoid treating "luxury" as a single price range when discussing Scottsdale.
Nationally, the top 10% threshold fell to $1,200,005 in August, down 4% both month over month and year over year. The top 5% threshold was $1,894,230, while the top 1% began at $5,163,712. Luxury homes also took longer to sell than the overall market, although all three luxury tiers moved four days faster than they did a year ago.
The Phoenix-Mesa-Chandler figures are still metro-wide listing data rather than Scottsdale-only sales data. I would use the $1.24 million threshold to understand where the metro's upper 10% begins, not as a pricing benchmark for an individual Scottsdale home.
What I Am Watching Going Into September
The first number I want to see in September is closed sales. August's 13.13% monthly decline was large enough to push months of supply above four even as active inventory fell. If closings recover, that supply figure can move fairly quickly without requiring a major change in inventory.
The second is under-contract activity. August's 4.14% increase was one of the few demand indicators that improved from July. If those contracts convert into September closings and the pending count continues to build, August may end up looking more like a late-summer slowdown than the beginning of a deeper pullback.
I am also watching pricing. The national market entered September with price reductions back at last year's rate, while Phoenix-Mesa-Chandler remained well above the national level. Locally, ARMLS new-list pricing increased in August even as closed pricing softened. Those numbers need another month before I would call the direction.
August left buyers with more time and sellers with a smaller margin for pricing mistakes. The broader Phoenix-area market carried more supply relative to its sales pace, but the improvement in under-contract activity keeps me from reading the month as a straight decline in demand. September should tell us whether that contract activity turns into more closings.
If you're considering buying or selling in Scottsdale, Paradise Valley, Arcadia, or elsewhere in the Phoenix metro, I can break these numbers down for the neighborhood and price range that actually applies to your property.
Cody Wolfe is a real estate broker and Partner at The Agency Scottsdale, representing buyers and sellers across Scottsdale, Paradise Valley, McCormick Ranch, and Arcadia.